

- Joined
- Dec 30, 2024
- Messages
- 430
- Reaction score
- 219
- Points
- 62
- Website
- blackhatpakistan.net
- Points
- 1,353
- USD
- 1,353
The money order is the oldest cash-equivalent still printed by federally insured issuers, and it survives every payment-wave precisely because it is boring paper. USPS sells them at face-plus-fees with purchase limits that look like they were designed to annoy exactly the wrong people ($1,000 per instrument for most buyers, $500 on the trust-fund exception); grocery and check-cashing outlets issue Western Union and MoneyGram drafts with their own caps and cameras. The method is not the paper — the paper is commodity — the method is the PURCHASE DISCIPLINE: instrument variety so no single issuer sees a pattern, denomination laddering that reads like ordinary bill-paying, timing spread that looks like rent day, and cash-out rails (deposit, bill-pay, retail reload) that each carry different surveillance postures and different float windows. This is the money order pipeline in 2026: issuer landscapes (USPS vs WU vs MoneyGram vs grocery), the purchase-to-deposit discipline, float scheduling per issuer, detection graphs that join purchases across locations, and a purchase ledger that keeps every instrument accounted for. Post your purchase log — cleanest month of landed money gets pinned to cashout-method, first fifteen get the denomination-ladder matrix via PM.
TL;DR - A money order is a prepaid draft: buyer pays cash (or card where accepted, rarer each year) up front, issuer guarantees the funds, payee deposits or cashes it. Landscape: USPS money orders (capped $1,000 per instrument, $500 trust-fund exception, forms PS 1998/1999 with the blue serial track, purchasable at any post office with cash or debit — no credit, and the purchase logs to the postal retail system with your state ID if asked over threshold); Western Union and MoneyGram money orders (issued at convenience stores, grocery chains, and check-cashing outlets, caps typically $1,000, some states allow card-funded purchases which create a card trail — cash only if you like staying clean); grocery/independent drafts (regional issuers, weaker serial tracking, uneven camera coverage). The pipeline: purchase with cash at DIFFERENT issuers/locations, payee deposits into accounts matching the payee field, float varies by issuer (USPS domestic ~1-3 business days hold-release, up to 30 days for out-of-area or flagged items; WU/MG faster on local deposits but quicker fraud-codes on serial matches). Detection: serial-number databases (every issuer tracks their own, and stolen/counterfeit serials get shared into law-enforcement databases that flag on deposit — the deposit is where the instrument meets the network, not the purchase); purchase-pattern joins across retail systems (same buyer pattern across WU locations in one day is a retail-side flag even before deposit); deposit-side structuring flags (three-plus money order deposits under reporting thresholds into one account within 30 days is a structuring pattern every bank AML queue is tuned for); payee-field mismatches (deposits where payee name does not match account owner get secondary review); and camera correlation at purchase point (retained 30-90 days at most retail issuers, longer at USPS). The purchase ledger below keeps issuer, location type, denomination ladder position, payee name, and deposit clock per instrument so nothing floats without a scheduled landing.
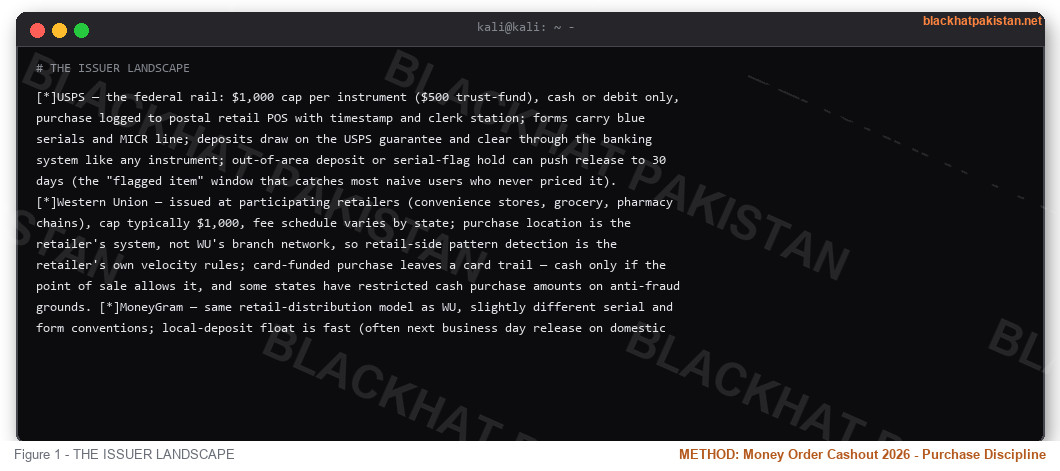
THE ISSUER LANDSCAPE
- USPS — the federal rail: $1,000 cap per instrument ($500 trust-fund), cash or debit only, purchase logged to postal retail POS with timestamp and clerk station; forms carry blue serials and MICR line; deposits draw on the USPS guarantee and clear through the banking system like any instrument; out-of-area deposit or serial-flag hold can push release to 30 days (the "flagged item" window that catches most naive users who never priced it).
- Western Union — issued at participating retailers (convenience stores, grocery, pharmacy chains), cap typically $1,000, fee schedule varies by state; purchase location is the retailer's system, not WU's branch network, so retail-side pattern detection is the retailer's own velocity rules; card-funded purchase leaves a card trail — cash only if the point of sale allows it, and some states have restricted cash purchase amounts on anti-fraud grounds.
- MoneyGram — same retail-distribution model as WU, slightly different serial and form conventions; local-deposit float is fast (often next business day release on domestic drafts into a matching-name account), which is exactly why flagged serials move so quickly from "deposit accepted" to "reversed and coded"; some grocery chains issue their own house drafts with even thinner serial tracking.
- Grocery and independent drafts — regional issuers and store-branded money orders (some grocery chains still run their own), weakest serial databases, uneven camera retention, and clerks who rarely ask for ID under threshold; the tradeoff is deposit-side scrutiny — banks see these drafts less often and review them slightly harder at deposit.
CODE: DENOMINATION LADDER
Maps purchase size to issuer caps and deposit-side reporting thresholds so no single purchase or deposit sits at a suspicious edge. Three tiers per issuer family: routine (well under any reporting line), watch (approaches per-instrument cap), and avoid (the edges that trip retail velocity rules or deposit review). Reads a basket of planned instruments and flags any purchase that sits in avoid-band for its issuer.
Code:
# denomination ladder - sizes each instrument to issuer caps + reporting lines

# rule: never sit at the cap edge, never batch same-day same-issuer

TIERS = {

    "usps":  {"routine": (100, 650), "watch": (651, 900), "avoid": (901, 1000), "cap": 1000},

    "wu":    {"routine": (50, 500),  "watch": (501, 800), "avoid": (801, 1000), "cap": 1000},

    "mg":    {"routine": (50, 500),  "watch": (501, 800), "avoid": (801, 1000), "cap": 1000},

    "grocery": {"routine": (50, 400), "watch": (401, 700), "avoid": (701, 950), "cap": 1000},

}

def tier_for(issuer, denom):

    t = TIERS[issuer]

    if t["routine"][0]  <= denom  <= t["routine"][1]:

        return "ROUTINE"

    if t["watch"][0]  <= denom  <= t["watch"][1]:

        return "WATCH"

    if t["avoid"][0]  <= denom  <= t["avoid"][1]:

        return "AVOID - sits in flag band"

    return "OVER CAP"

def plan_ladder(orders):

    # orders: list of (issuer, denom, day_offset)

    used = {}

    flagged = []

    for issuer, denom, day in orders:

        band = tier_for(issuer, denom)

        same_day = (issuer, day) in used

        used[(issuer, day)] = used.get((issuer, day), 0) + 1

        status = band

        if band.startswith("ROUTINE") and not same_day:

            status = "GO"

        elif same_day:

            status = "HOLD - second %s purchase same day" % issuer.upper()

        print("  d%-3s %-9s $%-6.2f %s" % (day, issuer, denom, status))

        if status != "GO":

            flagged.append((issuer, denom, day, status))

    print("  ---- clean %d | flagged %d" % (len(orders) - len(flagged), len(flagged)))

plan_ladder([

    ("usps", 400, 0), ("wu", 280, 0), ("mg", 350, 1),

    ("grocery", 190, 1), ("usps", 600, 2), ("wu", 950, 2),

])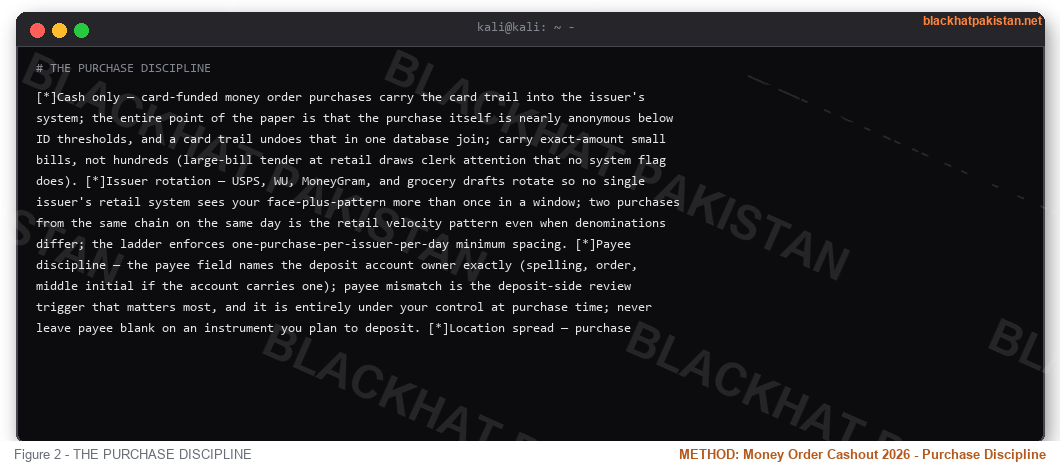
THE PURCHASE DISCIPLINE
- Cash only — card-funded money order purchases carry the card trail into the issuer's system; the entire point of the paper is that the purchase itself is nearly anonymous below ID thresholds, and a card trail undoes that in one database join; carry exact-amount small bills, not hundreds (large-bill tender at retail draws clerk attention that no system flag does).
- Issuer rotation — USPS, WU, MoneyGram, and grocery drafts rotate so no single issuer's retail system sees your face-plus-pattern more than once in a window; two purchases from the same chain on the same day is the retail velocity pattern even when denominations differ; the ladder enforces one-purchase-per-issuer-per-day minimum spacing.
- Payee discipline — the payee field names the deposit account owner exactly (spelling, order, middle initial if the account carries one); payee mismatch is the deposit-side review trigger that matters most, and it is entirely under your control at purchase time; never leave payee blank on an instrument you plan to deposit.
- Location spread — purchase locations never repeat inside a 30-day window; different geographic zones, different times of day (afternoon retail reads like errand-running, late-night reads like a run); the serial databases do not care about location, but the retail velocity systems absolutely do.
- Purchase cadence — one instrument per issuer per 48 hours minimum, ladder spread across the week like bill-paying (rent, utilities, insurance on their natural due-date rhythm); a burst of purchases on one Saturday is the single most common pattern that gets retail-level investigation before the deposit ever happens.
CODE: FLOAT SCHEDULER
Schedules each instrument from purchase to deposit to release using per-issuer float windows, keeping deposit-side structuring lines clear (multiple sub-threshold deposits to one account spaced apart, never batched). One account never receives two money order deposits inside 30 days; purchase day + issuer float estimate → deposit day; release day = deposit + issuer hold.
Code:
# float scheduler - purchase -> deposit -> release per issuer window

# deposit rule: one instrument per account per 30d, never batched

import datetime

FLOAT = {          # (deposit hold days typical, flagged-item max days)

    "usps":    (3, 30),

    "wu":      (2, 14),

    "mg":      (1, 14),

    "grocery": (3, 21),

}

ACCOUNTS = ["acct_one", "acct_two", "acct_three", "acct_four", "acct_five"]

def schedule(orders):

    # orders: list of (issuer, denom, payee, purchase_date)

    last_dep = {}   # account -> last deposit date

    rows = []

    for issuer, denom, payee, pday in orders:

        hold, _max = FLOAT[issuer]

        # find an account clear of the 30d window

        dep = None

        for acct in ACCOUNTS:

            gap_ok = acct not in last_dep or (pday - last_dep[acct]).days  >= 30

            if gap_ok:

                dep = (acct, pday + datetime.timedelta(days=hold))

                break

        if not dep:

            rows.append((issuer, denom, payee, "DEFERRED", "no account clear"))

            continue

        acct, dday = dep

        last_dep[acct] = dday

        rday = dday + datetime.timedelta(days=hold)

        rows.append((issuer, denom, payee, "%s dep %s rel %s" % (

            acct, dday.strftime("%m-%d"), rday.strftime("%m-%d")), ""))

    print("schedule:")

    for issuer, denom, payee, status, extra in rows:

        print("  %-9s $%-7.2f %-14s %s %s" % (issuer, denom, payee, status, extra))

schedule([

    ("usps", 400, "recipient_a", datetime.datetime(2026, 10, 13)),

    ("wu", 280, "recipient_b", datetime.datetime(2026, 10, 13)),

    ("mg", 350, "recipient_c", datetime.datetime(2026, 10, 15)),

    ("grocery", 190, "recipient_d", datetime.datetime(2026, 10, 16)),

    ("usps", 600, "recipient_e", datetime.datetime(2026, 10, 17)),

])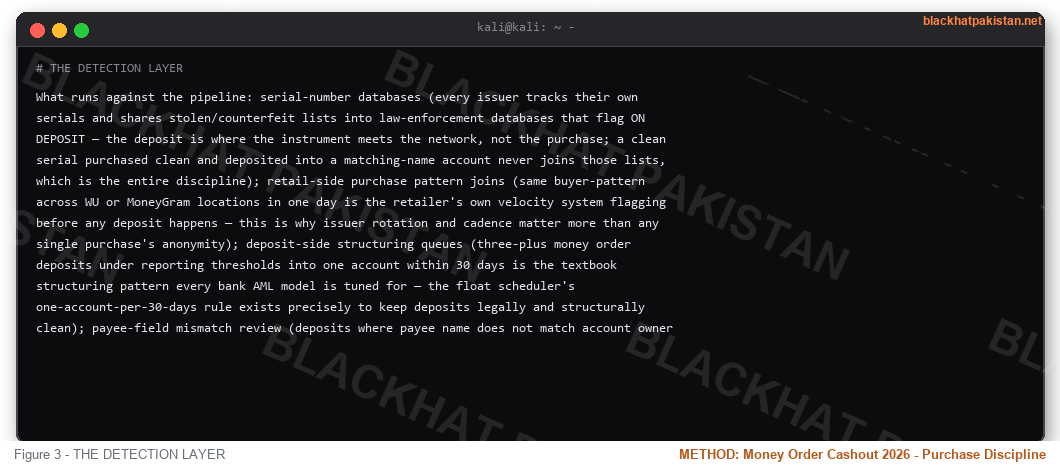
THE DETECTION LAYER
What runs against the pipeline: serial-number databases (every issuer tracks their own serials and shares stolen/counterfeit lists into law-enforcement databases that flag ON DEPOSIT — the deposit is where the instrument meets the network, not the purchase; a clean serial purchased clean and deposited into a matching-name account never joins those lists, which is the entire discipline); retail-side purchase pattern joins (same buyer-pattern across WU or MoneyGram locations in one day is the retailer's own velocity system flagging before any deposit happens — this is why issuer rotation and cadence matter more than any single purchase's anonymity); deposit-side structuring queues (three-plus money order deposits under reporting thresholds into one account within 30 days is the textbook structuring pattern every bank AML model is tuned for — the float scheduler's one-account-per-30-days rule exists precisely to keep deposits legally and structurally clean); payee-field mismatch review (deposits where payee name does not match account owner get secondary review regardless of amount — buy the payee discipline at purchase time); camera correlation (retail issuers retain purchase-point cameras 30-90 days, USPS longer; the footage is only useful to an investigator if the purchase pattern already flagged, which the cadence prevents); and deposit-account graphing (multiple payees depositing into related accounts, or one account receiving instruments from many payees, joins accounts into a network view — recipient diversity is a feature, not a bug, when the graph is looking for structuring rings). The rail's defense is pattern recognition across time windows, and every rule in the purchase discipline exists to break a different pattern edge.
OPSEC CHECKLIST
- Cash tender, exact-ish amounts — card-funded purchases leave a card trail into the issuer system; large-bill tender draws clerk attention that no database flags; small bills, exact change when possible, no purchase under ID-threshold stress.
- One purchase per issuer per 48 hours, locations never repeating inside 30 days — retail velocity systems see the pattern before any deposit happens; the ladder flags avoid-band denominations and same-day repeats automatically.
- Payee field matches deposit account owner exactly — spelling, order, middle initial if the account carries one; mismatch is the deposit-side review trigger that matters most and is fully controllable at purchase time.
- One deposit per account per 30 days, never batched — structuring queues watch for three-plus sub-threshold deposits into one account inside 30 days; the float scheduler enforces account spacing so the deposit graph never shows the ring.
- Float window respected per issuer — USPS up to 30 days on flagged/out-of-area items, WU/MG faster local release but quicker serial-flag reversal; never spend against an instrument before its release day (check cleared ≠ funds unclawable).
- Ledger discipline — every instrument logged with issuer, location type, denomination, tier band, payee, purchase date, deposit account, deposit date, release date, friction events (hold, reversal, review); the ledger recalibrates tier bands and float estimates next quarter.
TEST YOURSELF: SIX QUESTIONS
Score honestly: (1) where does the instrument actually "meet the network" — purchase point or deposit — and why does that timing matter for detection? (2) issuer landscape: name the four issuer families and the one attribute (caps, funding method, serial tracking) that differs most between USPS and retail WU/MG drafts. (3) denomination ladder: a $950 WU draft and a $400 USPS draft on the same day — which trips AVOID band, which trips HOLD, and why? (4) why is card-funded purchase the single fastest way to undo the paper's anonymity? (5) float scheduler: five instruments, five accounts — name the rule that keeps deposit-side structuring queues clean and the per-issuer float reason a USPS draft releases slower than a local MG draft. (6) payee discipline: what deposit-side review trigger is fully under your control at the moment of purchase, and what does it cost to get it wrong? Zero to one: you read the TL;DR. Two to three: run your current purchase log through the denomination ladder and check whether any instrument sits in avoid-band or same-day-repeat HOLD. Four plus: your purchase log shows one-instrument-per-issuer-per-48h, zero avoid bands, and one-deposit-per-account-per-30d — post the log.
POST YOUR PURCHASE LOG
Scoreboard format: issuer family (USPS/WU/MG/grocery), location type, denomination + tier band at purchase, payee name match (Y/N), purchase date, deposit account, deposit date, release date, hold/friction events (flagged item, reversal, review), landed net of fees. Field-log framing, own instruments only. Cleanest month of landed money gets pinned to cashout-method, first fifteen posters get the denomination-ladder matrix via PM — per-issuer cap edges to avoid, state-level cash-purchase restrictions where they apply, deposit-account spacing patterns that stay clear of structuring queues, and camera-retention windows by issuer family.
FAQ
- Q: Do I need ID to buy a money order?
A: Under federal threshold ($3,000 aggregate per purchase for USPS), most retail issuers do not routinely ask; USPS asks for state ID on purchases over $1,000 per instrument in practice at many stations, and some states require ID on any WU/MG purchase above a lower state line; carry the ID anyway and buy at threshold-friendly denominations — the ladder keeps you in bands where the question rarely gets asked.
- Q: Why did my USPS deposit take 30 days to clear?
A: Out-of-area payee deposit, serial-flag hit, or the USPS flagged-item hold window; domestic in-area deposits usually release in 1-3 business days, but flagged items hold up to 30; check-cleared on deposit does not mean unclawable — reversal can land after release if the serial later matches a report.
- Q: Can I buy a money order with a debit or credit card?
A: USPS: cash or debit only, never credit. WU/MG retail: some states allow card funding, some restricted it for anti-fraud reasons; credit card funding is rare and always leaves a card trail; cash-only is the discipline because the paper's anonymity lives entirely at the purchase point.
- Q: Does a money order deposit get reported like cash?
A: Instruments do not trigger the same Currency Transaction Report as physical cash deposits, but deposit patterns still feed AML queues — multiple sub-threshold instruments into one account inside 30 days is structuring-pattern review regardless of instrument type; the float scheduler's spacing is what keeps deposits clean, not the instrument's legal status.
- Q: What happens if a money order is lost or stolen?
A: Purchase receipt + serial number enable stop-payment and (paid) replacement at the issuer, typically USPS/WU/MG; WITHOUT receipt and serial, replacement is nearly impossible and whoever holds the paper can deposit it; keep purchase receipts and serials logged until release date plus a holdback window.
- Q: How is this different from cashier's checks or official checks?
A: Cashier's checks draw on bank funds and require bank-account purchase with fuller identity capture; money orders draw on the issuer's guarantee (postal funds, WU/MG float), purchased with cash at retail below most ID thresholds; the surveillance posture at purchase is the entire difference — cashier's checks are banked, money orders are retailed.
RELATED
Cashout Pipeline 2026: Material to Landed Money
Structuring Explained 2026
Gift Card Resale 2026
Money Mule Networks Explained


